The mid-size personal loan market in 2026
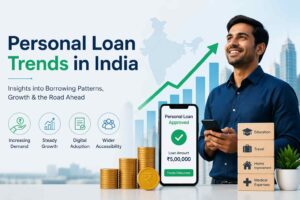
Mid-size personal loans occupy a distinct space between small short-term credit and larger instalment financing, typically covering needs too big for a quick advance but not large enough to require the underwriting depth of a mortgage or auto loan. Platforms like RadCred cater to these customers by providing loans with repayment terms that are longer than short-term credit, but shorter than traditional long-term loans. Understanding how this market functions in 2026 requires looking at demand drivers, underwriting shifts, and structural changes that separate it from adjacent lending categories.
Where does demand come from?
Demand in this segment comes largely from borrowers consolidating existing debt or covering expenses that don’t fit neatly into either small-dollar credit or larger secured lending. A person refinancing multiple smaller balances into a single monthly payment represents one common use case. Another involves covering a planned expense that exceeds what short-term credit products typically offer, without requiring the collateral or lengthy approval process tied to larger secured loans.
Borrowers in this range also tend to have more established credit histories than short-term credit applicants. This changes how lenders approach the relationship. There’s more data available upfront, which shifts underwriting away from behavioural proxies and toward more traditional credit evaluation, even as the overall process remains largely digital.
Is underwriting changing?
Underwriting for mid-size loans has moved toward hybrid models that combine traditional credit data with supplementary verification methods. A few specific shifts stand out:
- Income verification automation – Direct bank connections now allow income confirmation without manual document uploads, cutting processing time substantially.
- Debt-to-income emphasis – Lenders weigh existing obligations more heavily at this loan size than they typically would for smaller short-term products.
- Tiered approval speed – Straightforward applications clear quickly through automated systems, while borderline cases route to additional review layers.
This layered approach reflects the loan size itself. There’s enough at stake per transaction that lenders can’t rely purely on automated proxies the way short-term credit platforms often do, but the volume still demands more speed than traditional manual underwriting allows.
Repayment structure trends
Repayment terms in this segment have shifted toward more flexible scheduling options rather than a single fixed structure applied uniformly. Borrowers increasingly get offered choices between different term lengths at the point of approval, letting the monthly payment size adjust based on individual preference rather than a one-size-fits-all default.
This flexibility does add complexity on the servicing side. Platforms need systems capable of tracking multiple repayment structures simultaneously rather than a single uniform schedule across every account. That complexity has pushed servicing technology to evolve alongside underwriting, since a mismatch between flexible loan terms and rigid servicing infrastructure creates operational friction that shows up quickly in missed payment tracking.
Competitive positioning shifts
Competition in this segment has intensified as platforms originally built around short-term credit have expanded upward into mid-size lending. This expansion brings existing borrower data and established infrastructure into a new product category, giving these platforms an advantage over lenders entering the space without that prior foundation.
The challenge for traditional lenders is to adapt their infrastructure designed for slower, document-heavy lending processes to meet the speed expectations now standard across digital lending broadly.